Enterprise Value and Equity Value: what is the difference?
Enterprise value and equity value: what is the difference?
Enterprise value and equity value are closely related, but they represent two different measures of value. Understanding the distinction is important because the valuation of a company is not necessarily the same as the amount shareholders receive upon a sale.
For example, if a company is valued at SEK 50 million, this does not automatically mean that the owners will receive SEK 50 million for their shares.
What is enterprise value?
Enterprise value is the value of a company's operating business, independent of how the business is financed. In other words, it primarily reflects the business's ability to generate earnings and cash flow, rather than the extent to which it is financed by equity or debt. When a company is valued using, for example, an EBITDA or EBIT multiple, it is typically the enterprise value that is being calculated.
Assume a company has:
- EBITDA of SEK 10 million
- A valuation multiple of 8x EBITDA
The company's enterprise value is then:
SEK 10 million × 8 = SEK 80 million
The enterprise value is therefore SEK 80 million. However, this does not mean that the shares in the company are worth SEK 80 million.
What is equity value?
Equity value is the value of a company's shares and, consequently, the value that ultimately accrues to shareholders in the event of a sale. To move from enterprise value to equity value, one typically adjusts for the company's net debt or net cash.
Net debt can be simplified as:
Interest-bearing debt – cash and cash equivalents
A simplified formula is therefore:
Equity value = Enterprise value – net debt
In practice, however, the concept of net debt can be broader than just interest-bearing debt and cash. Items that, depending on the transaction, may be included in net debt or net cash include, for example:
- bank loans and other interest-bearing debt
- shareholder loans
- finance lease liabilities
- accrued interest
- corporate tax liabilities
- certain pension obligations
- cash and cash equivalents
- certain financial assets
There is no single definitive rule as to exactly which items should be classified as net debt or net cash in a transaction. The assessment depends on factors such as the transaction structure, the company's balance sheet, and what the buyer and seller agree.
The definition of net debt and net cash therefore often becomes an important part of the negotiations between the buyer and seller. For example, a buyer may regard a certain item as debt-like and seek to deduct it from the purchase price, while the seller may argue that the item forms part of normal operations and is therefore already reflected in the enterprise value.
If a company instead has a net cash position, the equity value will, all else being equal, be higher than the enterprise value.
A simple analogy: buying a property
A simple way to understand the difference between enterprise value and equity value is to compare it to a property.
Assume a property has a market value of SEK 10 million. This can be compared to the company's enterprise value, i.e. the value of the asset or business itself.
If there is also a bank loan of SEK 6 million attached to the property, the owner's net value is SEK 4 million. In simplified terms, this can be compared to the equity value, i.e. what a buyer would effectively pay for the owner's interest assuming the bank loan remains with the property.
Similarly, a company may have an enterprise value of SEK 80 million but, if the company has SEK 10 million in net debt, an equity value of SEK 70 million.
However, equity value can also be higher than enterprise value.
Assume instead that the property is worth SEK 10 million, that there are no loans attached to it, and that a safe containing SEK 2 million in cash is included in the transaction. A buyer might then, in simplified terms, be willing to pay SEK 12 million, corresponding to an equity value of SEK 12 million.
The same principle applies to an operating company: if the business is worth SEK 80 million and the company has a net cash position of SEK 10 million, the equity value can amount to SEK 90 million.
The analogy is highly simplified, but it illustrates the fundamental principle that enterprise value represents the value of the business, while equity value represents the value attributable to shareholders after taking net debt or net cash into account.
But the purchase price can be adjusted further
In a corporate transaction, the calculation often does not stop with the adjustment for net debt. It is also common for the purchase price to be adjusted based on the level of working capital in the company at closing.
Working capital typically consists of items such as:
- accounts receivable
- inventory
- accounts payable
- other short-term operating receivables and liabilities
The parties usually agree on a normalized level of working capital considered necessary for the business to operate normally. This normalized level is often determined with reference to average working capital over, for example, the previous 12 months, although factors such as seasonal variations, growth, and changes in the business may also need to be taken into account.
The underlying principle is that a normal level of working capital is included in the enterprise value, meaning that the buyer does not pay separately for the normalized level.
At closing, the actual working capital is then determined, typically through a set of closing accounts. If the actual working capital is higher or lower than the agreed normalized level, the purchase price is usually adjusted upward or downward.
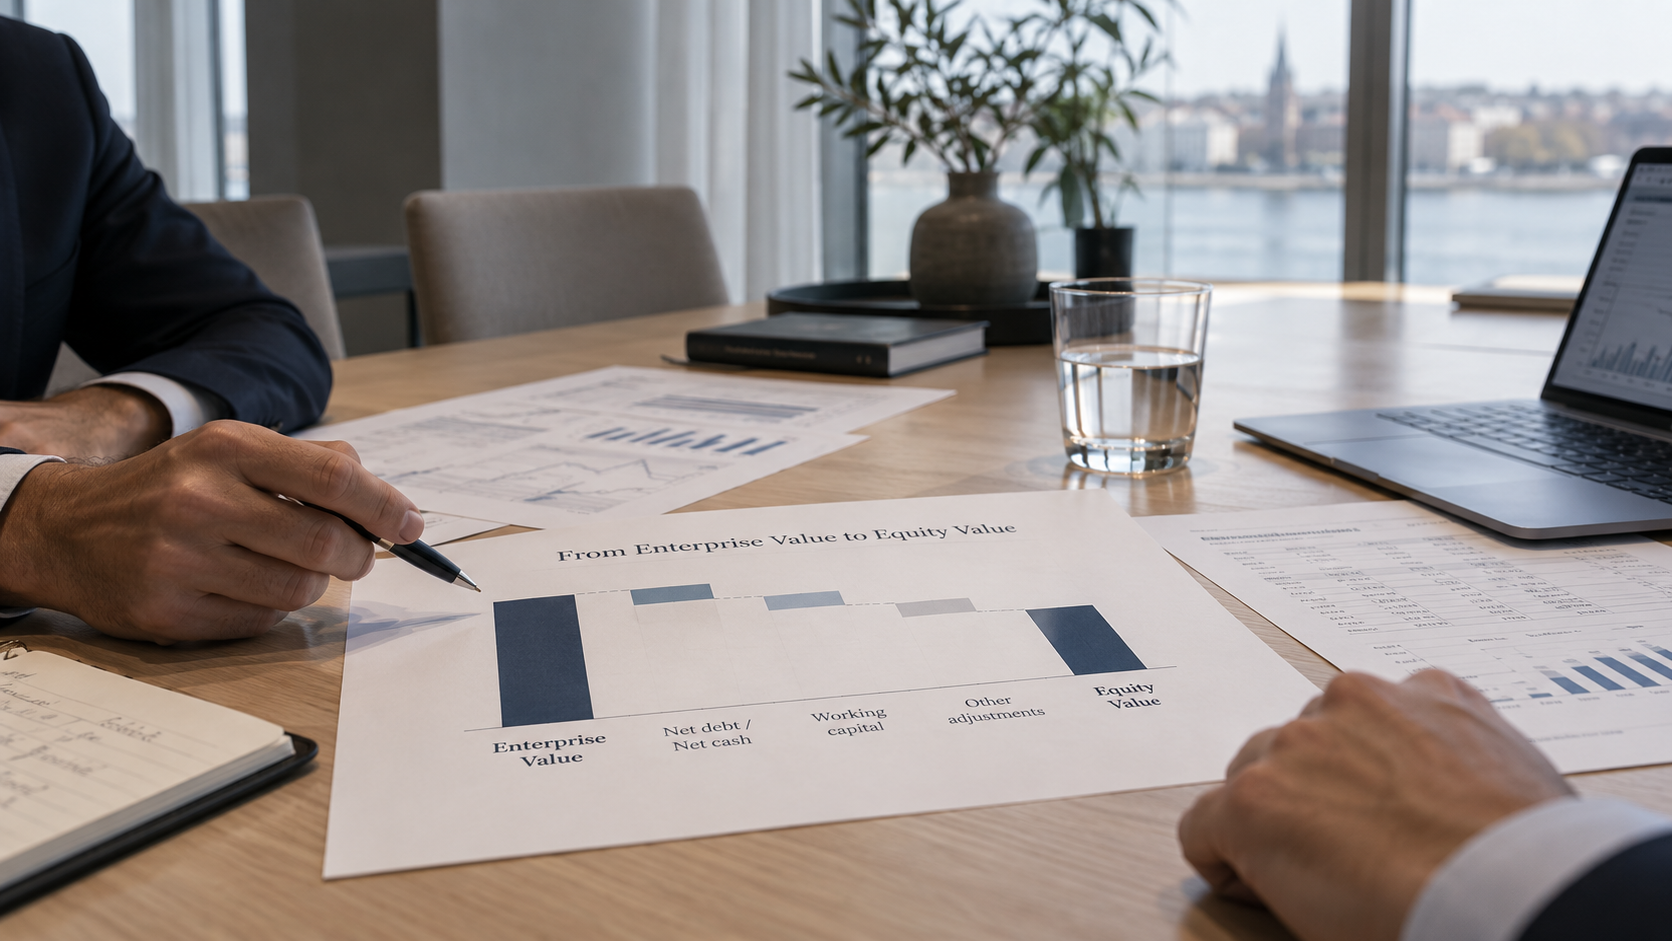
A simplified bridge can therefore look like this:
Enterprise value
– net debt
= Equity value
+/– working capital adjustment
= final purchase price
Why adjust for normalized working capital?
An important principle in a business sale is that the buyer should acquire a business with a normal level of working capital, i.e. sufficient accounts receivable, inventory, and other working capital items for the business to continue operating normally.
The working capital adjustment mechanism therefore serves an important purpose, including preventing the seller from increasing the company's cash balance at the expense of working capital prior to closing. For example, a company could increase its cash position before closing by:
- collecting accounts receivable faster than normal
- significantly reducing inventory purchases
- delaying payments to suppliers
These measures could result in a higher cash balance at closing, which, viewed in isolation, would increase the equity value, while at the same time leaving the business with a lower level of working capital than is required for normal operations.
By comparing actual working capital at closing with an agreed normalized level, the purchase price can be adjusted accordingly. The higher purchase price that a larger cash balance would otherwise imply is offset by a corresponding downward adjustment if working capital at closing is below the normalized level. In practice, this therefore becomes a zero-sum effect.
The mechanism thus helps ensure that the buyer acquires the business with a normal level of working capital, while the seller receives credit for the cash actually present in the company without being able to create an artificially higher value by depleting working capital.
Why is enterprise value used in business transactions?
Enterprise value is used because it reflects the value of the business itself, independent of how it is financed. This makes it easier to compare companies with different levels of debt and cash and therefore provides a natural starting point for a business valuation or transaction.
Furthermore, a buyer often does not have full visibility into the company's balance sheet when submitting an indicative offer and therefore may not have sufficient information to determine the final equity value. Indicative offers are therefore often expressed on an enterprise value basis, with adjustments for net debt, working capital, and other relevant items made at a later stage.
For owners considering a sale of their company, it is therefore important not to focus solely on enterprise value. It is equally important to understand the bridge from enterprise value to equity value and, ultimately, the final purchase price.
Can company owners optimize equity value before a sale?
Yes. There are often measures that can be taken ahead of a future business sale to help increase equity value, particularly if the process starts well in advance. These may include:
- reducing unnecessary debt
- releasing capital tied up in inventory or accounts receivable
- improving invoicing procedures and shortening customer payment terms
- negotiating more favorable payment terms with suppliers
- reviewing which items may be classified as net debt or net cash in a future transaction
At the same time, it is important that these measures do not adversely affect the business or its profitability.
FLB Partners is therefore happy to become involved well in advance of a planned business sale to work with the owners to identify opportunities to prepare the company and optimize equity value ahead of a future transaction.